Run the math on a single mid-size account and the problem shows up immediately: officers worked the hours this week, payroll clears Friday, and the invoice for those same hours won’t be paid by the client for another thirty, forty-five, sometimes sixty days. That’s the security guard payroll funding cash flow gap in its simplest form — you are financing your client’s accounts payable department out of your own checking account, one payroll run at a time, and the bigger the contract the bigger the float you’re carrying.
This isn’t a sign of a poorly run company. It’s the default shape of the business. Guards expect to be paid on a predictable weekly or biweekly schedule — that’s non-negotiable if you want to retain anyone in a labor market where officers can walk to a competitor paying the same bill rate. Commercial and institutional clients run their payables on their own calendar, and net-30 is often the fast end of what a large property management firm, hospital system, or municipality will agree to. Nobody designed this gap on purpose. It’s just what happens when a labor-intensive service business collides with enterprise procurement.
Why the security guard payroll funding cash flow gap gets worse as you grow, not better
The instinct is to think growth solves this — more contracts, more revenue, more cushion. It’s the opposite. Every new account you win adds another block of weekly payroll obligations before that account’s first invoice is even due, let alone paid. A company adding sites steadily can find itself perpetually thirty-plus days behind its own growth, where the cash needed to fund next month’s payroll always slightly exceeds what’s actually collected from last month’s billing. Growth without a plan for the gap doesn’t relieve the pressure — it compounds it, because you’re now floating payroll for more officers across more accounts at the same time.
The mechanics are simple once you see them: payroll is a fixed, short-cycle obligation tied to hours already worked, and receivables are a variable, long-cycle asset tied to a client’s internal approval chain. Fix one side or subsidize the gap between them — there’s no third option that doesn’t involve running out of cash mid-month.
The levers, and why none of them is automatically right
Billing cadence. The simplest lever is renegotiating how often you invoice, not how much you charge. Weekly or biweekly invoicing instead of monthly shortens the distance between hours worked and the invoice going out the door — it doesn’t change when the client pays, but it means you’re not sitting on four weeks of unbilled labor before the clock even starts on their net-30. This costs nothing except the administrative discipline to actually generate invoices on a tighter schedule, which is harder than it sounds once your billing person is also doing three other jobs.
Invoicing discipline. A shocking share of the cash-flow problem in this industry isn’t the client’s payment terms — it’s how long it takes the company itself to turn worked hours into an accurate invoice. If your billing runs off timesheets that need chasing down, or if disputes over hours worked delay approval, you’ve added your own internal lag on top of the client’s net-30, and that’s lag you control. A daily activity report and time and attendance record that ties directly to scheduled hours removes a step from that chain — there’s less to reconcile before an invoice goes out, and fewer grounds for a client to hold payment while they “verify hours.”
A line of credit. Borrowing against the gap is the most common fix, and for a company with steady, predictable receivables it’s often the cheapest per dollar — but it depends entirely on the company already having a banking relationship and a balance sheet clean enough to qualify, which a newer or thinly capitalized operator often doesn’t have.
Factoring or invoice financing. Selling receivables (or borrowing against them) to a factor closes the gap fast and doesn’t depend on the same underwriting a bank line does, since the security is the invoice itself, not the company’s overall credit. The tradeoff is that it’s built around margin — you’re paying to convert a receivable into cash sooner, and on already-thin guard-industry margins that cost is felt directly rather than absorbed.
None of these is a universal answer, and that’s the point: the right one depends on how fast you’re adding accounts, how strong your existing banking relationship is, and how much of the gap is genuinely the client’s payment terms versus your own invoicing lag. A company adding one steady account a quarter has a different problem than one that just won three sites in the same month. Sort out which piece of the gap is structural (net-30 is net-30) and which piece is operational (slow, disputed billing) before reaching for financing to paper over a problem that better invoicing discipline would have shrunk on its own.
The mistake that compounds the gap
The costliest version of this problem isn’t the timing gap itself — it’s a company that responds to a cash crunch by delaying its own payroll to officers, or quietly cutting hours to manage the float. Both fixes solve this week’s cash problem and create next month’s turnover problem, because officers who get paid late once start looking for the next job before the second late payroll happens. In an industry where the biggest recurring cost is finding and training a replacement, protecting the payroll date is usually worth more than protecting the bank balance on any single week. Whatever lever you pull to manage the net-30 gap, treat payroll as the fixed point and everything else — invoicing cadence, financing, negotiated terms with a client — as the variable that has to move around it.
It’s also worth pushing back, contract by contract, on terms you’ve simply inherited rather than negotiated. Not every client insists on net-30; some institutional accounts default to it because nobody on their side asked for anything shorter, not because their internal process actually requires it. A new contract is the easiest moment to ask for net-15 or a split invoice cycle, before net-30 becomes the assumed baseline for the relationship. It won’t work on every account, particularly large institutional or government clients with fixed payables cycles, but it costs nothing to ask, and shaving even one account down from thirty days to fifteen shrinks the float you’re carrying without touching your cost of capital at all.
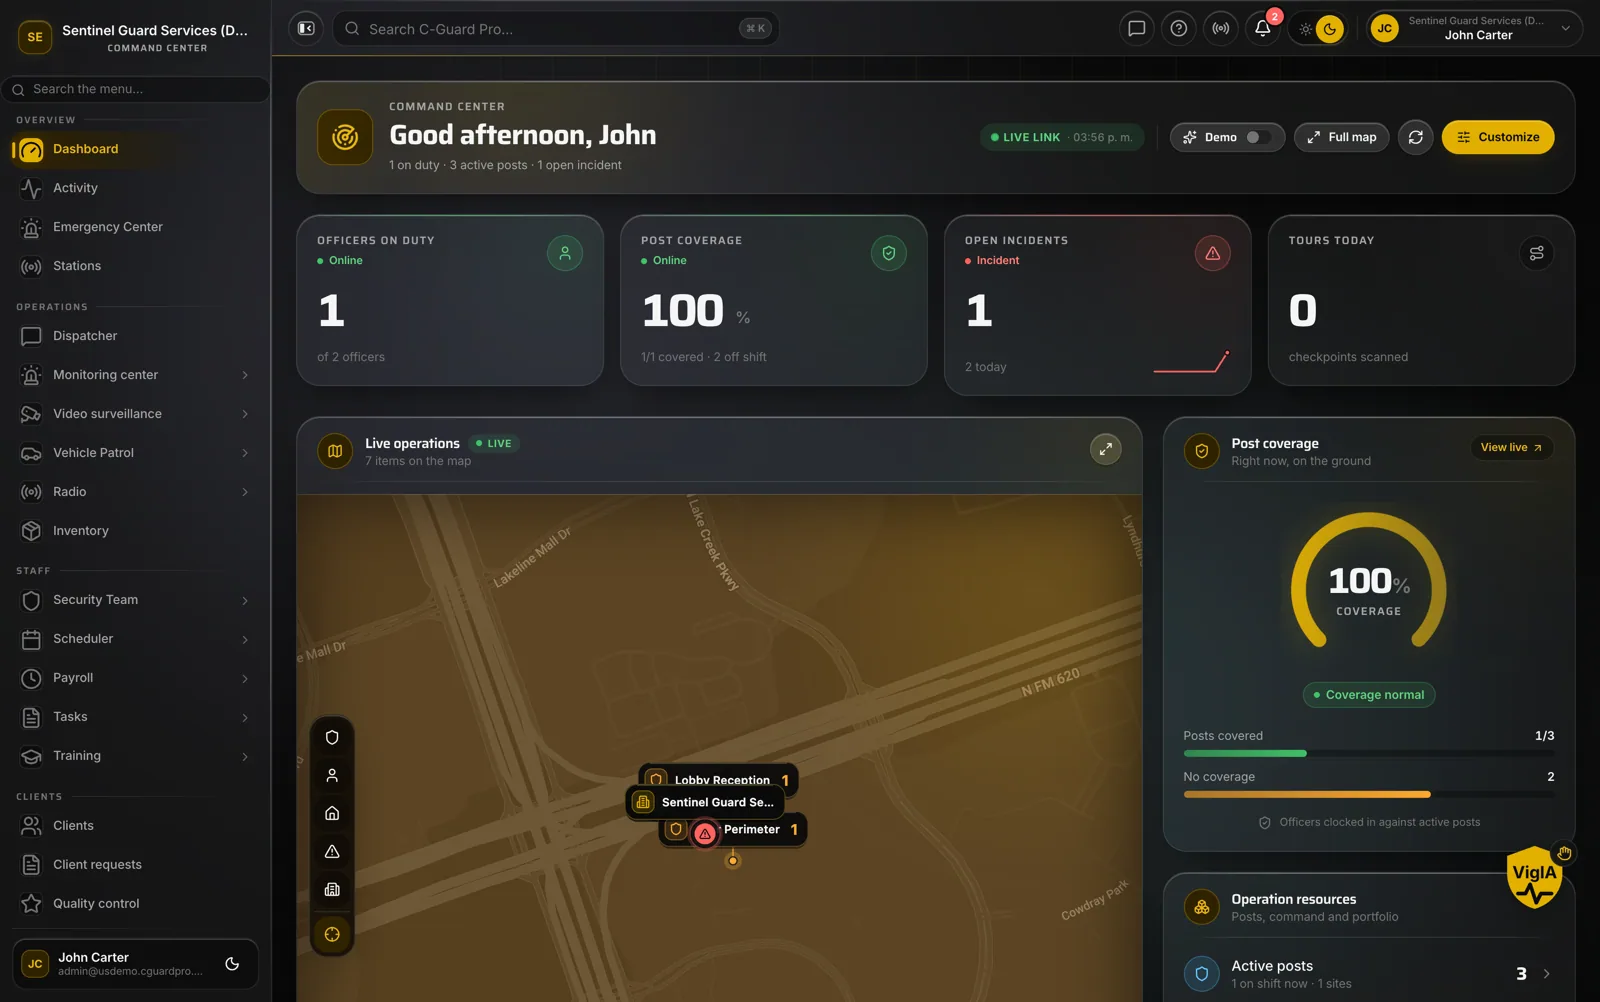
What this looks like operationally
None of the financial levers matter if the underlying data is slow or disputed. The fastest path from hours worked to cash collected runs through the same records that keep your operation running day to day: schedules that match what was actually posted, attendance that ties to those schedules, and reporting a client can review without a phone call. When a property manager can see, in real time, that a post was covered for the hours you’re billing, there’s less friction in the approval chain that sits between your invoice and their payment — and less of that internal delay compounding the net-30 you already can’t control.
If you want to see how tighter attendance and reporting can shorten your own invoicing lag, explore CGuardPro or get in touch.